Business van use
Van for business use is cover for vehicles used for work or business driving. Whether you're a tradesperson, contractor or own a business that relies on vans, van for business use will keep you protected when you’re out on the road.
Cover for everyday driving, work or business use. Manage it all in the app.
Van insurance is a type of policy that covers your van while it's being used for work or personal driving. It keeps you protected if you're involved in an accident, or your van is damaged or stolen.
As vans are different from regular cars, and typically used for different reasons, the insurance requirements tend to be different, too.
Whether you’re a self-employed tradesperson using your van for work, or a proud new van owner dreaming of weekend escapes, we’ve got you covered.
You pick a policy by how you use your van (personal, business or courier) and a level of cover. Fully Comprehensive is available on every van policy, and Third Party Only on courier policies.
Pick the cover that matches how you drive. Commuting, weekends and everyday trips need personal van use. Tools, jobs and business driving need business van use. Delivering other people's goods for payment needs courier van use, which includes hire and reward cover. Each card below explains who it suits and where to get a quote.
Commercial van insurance is another name for business van insurance, which covers a van you use for work. Our business van insurance page explains that policy in detail.
Business van use
Van for business use is cover for vehicles used for work or business driving. Whether you're a tradesperson, contractor or own a business that relies on vans, van for business use will keep you protected when you’re out on the road.
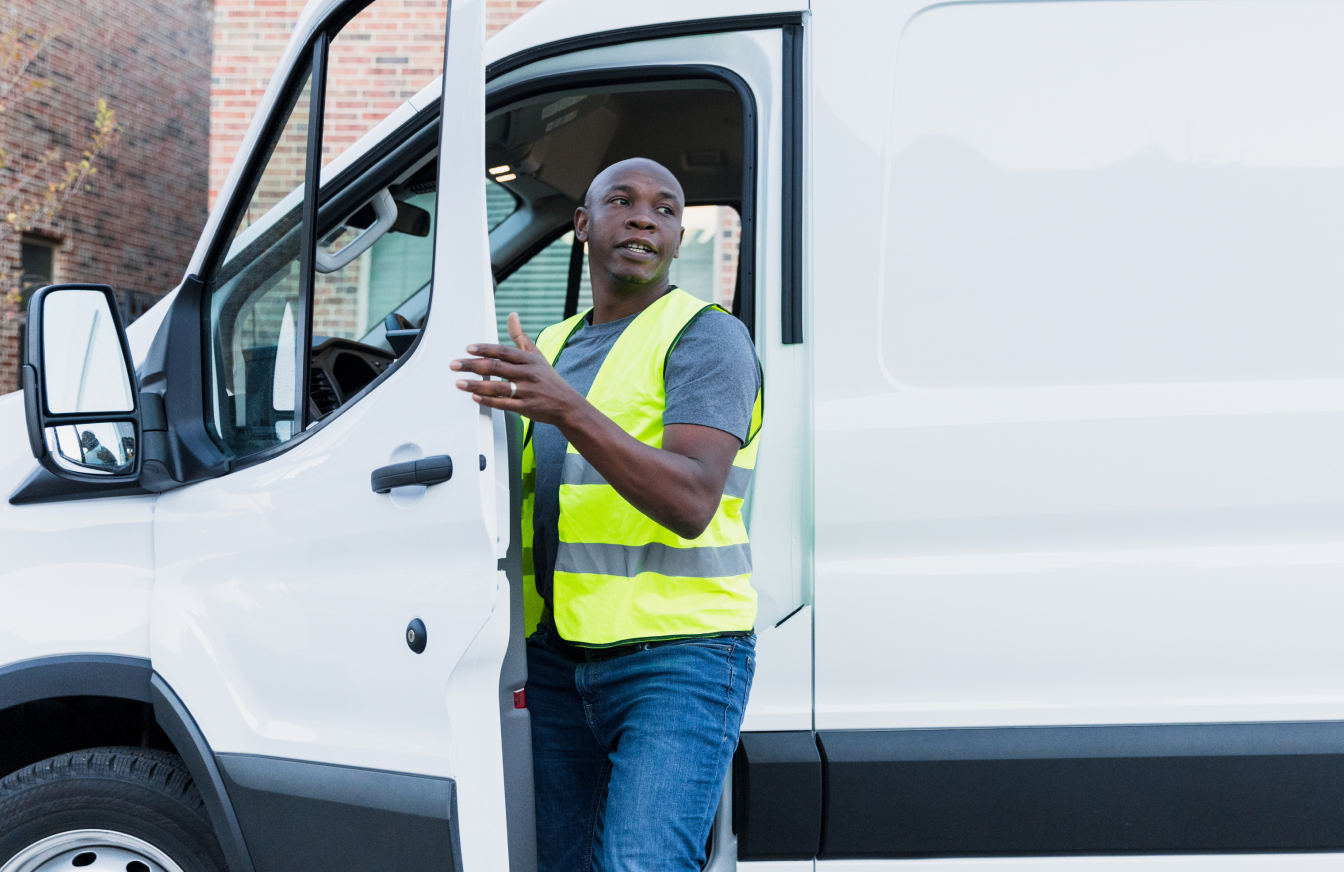
Courier van use
Van for courier use covers drivers who use a van to deliver third party goods. You might hear it referred to as carriage of goods for hire and reward, or simply van delivery insurance. Whether you deliver packages, parcels, documents or furniture, this is the type of cover you need.
Personal van use
Van for personal use, also known as private van use, covers you and your van for everyday driving. You might hear it referred to as social, domestic and pleasure van (or SDP for short). It covers you for things like weekends away, hobbies and visiting friends, but it doesn’t cover you for work or business use.
Getting a van insurance quote with Zego takes a few minutes online. Pick the use that matches your work: personal, business or courier. Then tell us about your van, how you drive and any claims, and we'll build your quote for that use. You can pay in one go or monthly, and paying annually usually costs less.
Have these to hand: your name and address, the van's make, model, registration and value, any no claims bonus, and any alarm, immobiliser or tracker fitted. The full list is under 'What details do I need to get a quote?' further down this page.
When choosing a van insurance policy, you'll need to decide what level of cover is right for you. Here are the two main types we offer (depending on the type of policy):

Third Party Only
This is the minimum legal requirement, and is only available with our courier van insurance. It covers you for damage to third-party property or injuries caused to others. However, it doesn't cover you or your van.

Fully Comprehensive
This is the highest level of protection. With our comprehensive cover, you get all the protection of a third party policy, plus cover against theft or damage to your vehicle. You can also choose add-ons to boost your cover.
Third Party Only is available on courier van policies. Fully Comprehensive is available on every van policy we offer. Here is what each one pays for.
Accidental damage: This will cover you for repairs or the replacement of your van if it's damaged in an accident.
Third party liability: If you're a courier and you accidentally injure someone or damage their property while working, this covers any legal fees or compensation payouts you might have to pay.
Personal belongings: If your tools, equipment or personal belongings are lost or damaged, this will cover the costs (limits may apply).
Theft and vandalism: If your van is damaged or targeted by thieves, you’ll be covered for any recovery costs or repairs.
Fire and natural disasters: This is protection against damage or loss caused by fire, floods, storms or other natural disasters.
Windscreen and glass: Most comprehensive van insurance policies cover the repair or replacement of damaged windscreens and windows (again, limits may apply).
You may be able to upgrade your van insurance policy with optional extras like breakdown cover and replacement vehicle cover.

Breakdown cover
Get help if your van breaks down, including roadside recovery and repairs to get you back on the road.

Replacement vehicle cover
Get a replacement van while yours is being repaired or replaced, allowing you to keep working.
There is no single price. Every quote is built from the details you give us, and a handful of them move the price more than the rest.
Paying annually usually costs less than paying monthly. On a Sense policy, good driving with the Zego Sense app can mean a better price at renewal.
1. Your van
Make, model, age, value and insurance group all count. Bigger, faster and pricier vans cost more to repair and replace, so they cost more to insure.
2. How you use it
Personal, business and courier use carry different levels of risk. Couriers drive more miles at busier times, so courier cover usually costs more than personal cover.
3. Your driving history
Your age, how long you have held your licence, and any claims or convictions in the past few years all feed into the price.
4. Your no claims bonus
Each claim-free year builds a discount. Tell us how many years you have when you get a quote.
5. How you secure it
An alarm, immobiliser or tracker makes your van harder to steal, and that can bring the price down.
6. Who else drives it
Adding drivers, especially young or inexperienced ones, can push the price up. Add only the people who really need to drive the van.
Personal information: Your name, address and contact details, plus the details of any other drivers who will be using the van.
Driving history: Details about your driving experience, including any convictions or claims you’ve made in the past.
Intended use: Tell us how the van will be used, whether that's for making deliveries, transporting your own tools and equipment, or everyday driving.
Vehicle details: We'll need the make, model, registration number and approximate value of your van.
No claims bonus: If you have one, give us the details of any no claims bonus you've earned on previous policies. It could help to lower the cost of your cover.
Extra security features: We may also need to know about any extra technology or security features installed in your van, such as immobilisers, alarms or trackers.

81m
policies sold

575k
drivers have chosen us

96%
of Sense drivers save money
While the cost of van insurance quotes will vary depending on lots of different factors, here are a few things you can do to help reduce the cost of yours.
(Keep in mind that while cost is important, buying a cheap van insurance policy might not give you the cover you need. So try to balance price with the level of protection that your business needs.)
1. Check your named drivers
Including only essential drivers on your policy can help to reduce the cost. If a driver isn’t likely to use the van, it might be better to leave them off the policy. Also, adding inexperienced or high-risk drivers can increase the amount you pay.
2. Build your No Claims Bonus
By driving safely and maintaining a good claims history, you can help to earn a discount each time you renew.
3. Secure your van
Enhancing your van’s security with alarms, immobilisers, or a tracking device can reduce your insurance premium. Parking in a secure area overnight, such as a garage or gated space, may also lower costs, as insurers view well-protected vans as lower risk.
4. Compare different quotes
Be sure to get quotes from more than one van insurance provider. It’ll help you to compare policies and make sure you’re getting the best value for your cover.
5. Pay annually
Paying for your policy annually instead of monthly can result in significantly lower costs over the long run.
6. Use Zego Sense (Telematics app)
Using a telematics app, such as Zego Sense, allows insurers to monitor your driving habits. Good driving is rewarded with savings, as the app tracks factors such as speed, braking, and overall driving behaviour, offering responsible drivers the chance to lower their premiums.
'Best' depends on how you use your van, so here's a straight answer. Zego is a good fit if you want cover built around how you use your van, with hire and reward included on courier policies. It also suits you if you'd rather manage your policy in the app than on the phone. On a Sense policy, good driving with the Zego Sense app can mean a better price at renewal.
We're not the right fit for everyone. We don't offer fleet cover, so if you run several vans you'll need another provider. We sell two levels of cover: Third Party Only on courier policies, and Fully Comprehensive on every policy. If you want Third Party, Fire and Theft, you'll need to look elsewhere. We're an insurer, not a comparison site, so get a quote from us and at least one other provider before you decide.
Report it as soon as you can. There are three steps, and the app is the fastest way to start.

1. Contact us
Report the incident in your Zego app, or use the online claims form on our claims page.

2. Get support
A claims handler takes the details and guides you through what happens next.

3. Get back on track
We process the claim and keep you updated in the app until it is settled.
When it comes to van insurance, the type of policy you need depends on the way you use your vehicle. Here are the two main types we offer:
1. Business van use
Van for business use (also known as carriage of own goods), is cover for vehicles used for work or business purposes. It typically covers you for commuting, carrying goods, and transporting tools and equipment from one place to another.
2. Courier van use
Van for courier use is cover for drivers and couriers who use a van to deliver goods. It’s sometimes referred to as carriage of goods for hire and reward. Whether you deliver packages or documents, van for courier use keeps you protected while you’re working.
3. Van for personal use
Van for personal use, also known as private van use, covers you and your van for everyday driving. You might hear it referred to as social, domestic and pleasure (or SDP for short). With this policy, you’re covered for all types of social driving, but you’re not covered for work or business use.
To work as a courier, you need a type of van insurance called hire and reward (H&R). It covers you for making deliveries in your own vehicle.
You’ll also need a social, domestic and pleasure (SD&P) policy — that’s the usual type of private van insurance you have for personal driving, like trips to the shops or visiting friends.
Make sure that your H&R policy includes legal and public liability insurance (ours does). That will keep you protected if you’re involved in an accident and found to be at fault.
Courier insurance can be a bit more expensive than regular car insurance, as the risk of being involved in an accident is higher.
As a courier or delivery driver, you’re likely to drive more miles than a regular driver, and at busier times of the day, too. This increases your risk of being involved in a collision, which pushes the cost up.
As with any motor insurance, it’s good to get a few quotes before you buy. It’ll help you to find the right courier van insurance for your budget.
While the cost of van insurance quotes will vary depending on lots of different factors, here are a few things you can do to help reduce the cost of yours:
1. Check your named drivers
Including only essential drivers on your policy can help to reduce the cost. If a driver isn’t likely to use the van, it might be better to leave them off the policy. Also, adding inexperienced or high-risk drivers can increase the amount you pay.
2. Build your No Claims Bonus
By driving safely and maintaining a good claims history, you can help to earn a discount each time you renew.
3. Compare van insurance quotes
Be sure to get quotes from more than one van insurance provider. It’ll help you to compare policies and make sure you’re getting the best value for your cover.
4. Pay annually
Paying for your policy annually instead of monthly can result in significantly lower costs over the long run.
Keep in mind that while cost is important, buying a cheap van insurance policy might not give you the cover you need. So try to balance price with the level of protection that your business needs.
The cost of van insurance usually differs from car insurance, and can sometimes be more expensive. The actual cost you’ll pay depends on a few things, including the type and value of your van, the way you use it, and your driving history.
As vans are often used for business or work purposes, the cost of van insurance can be higher than private car insurance. But by keeping a clean driving history, choosing the right model of van, and taking a few extra steps, you should be able to find a cheap van insurance policy that fits within your budget.
To get a van courier policy with us, you’ll need to meet the following criteria:
- You have a full UK driving licence
- You are aged 21 - 64
- You live and work in England, Scotland, or Wales
- Your vehicle has 9 seats or fewer (including the driver’s seat)
- You’ve had no more than 2 claims in the last 3 years (regardless of fault)
Other criteria may apply, so it’s a good idea to check before getting a quote.
Often, yes. Vans are bigger, carry more and tend to do more miles, so repairs and claims cost more. Your van's insurance group, how you use it and your driving history decide most of the difference. Building a no claims bonus and securing your van both help bring the price down.
Usually not. Most car policies do not cover vans, and 'driving other cars' cover almost never does. Check your policy wording before you drive, or read our guide 'Can I drive a van on my car insurance?' on the Zego blog.
Yes. Personal van insurance covers social driving but not commuting or any work use, so driving to and from a job needs business van cover. If you carry tools or visit sites for work, business van cover is the right fit too.
Yes. You can add named drivers when you get a quote. Add only the people who really need to drive the van, because inexperienced or high-risk drivers push the price up. Any-driver policies work differently, and our guide to any driver van insurance explains how.
Every van model sits in an insurance group based on its value, performance, security and repair costs. Lower groups are cheaper to insure. Our van insurance groups guide lists popular models by group so you can compare before you buy.
Sometimes. Some insurers accept a no claims bonus built up on a car policy and others do not, and you can normally only use it on one policy at a time. Tell us your no claims history when you get a quote, and read our guide to no claims bonus for van insurance for the detail.
Online, in a few minutes. Choose the use that matches your work: personal, business or courier. Then give us your details, your van's make, model, registration and value, your driving history and any no claims bonus. Fully Comprehensive is available on every van policy, and Third Party Only on courier policies. You can pay in one go or monthly.
Commercial van insurance, which we call business van use, covers a van you use for work, such as carrying your own tools, stock or equipment. Personal van insurance covers social and everyday driving, with no work or business use. If you deliver other people's goods for payment, you need courier van insurance instead. Our guide to commercial versus personal van insurance goes through the differences.
It depends on what you could afford to lose. Third Party Only is the legal minimum and is only available on our courier van policy. It pays for damage you cause to other people and their property, but nothing for your own van. Fully Comprehensive adds cover for accidental damage, theft, fire, and windscreen and glass (limits apply) on the van you earn with. It costs more, so weigh that against what it would cost you to repair or replace your van yourself.
Join the good driving revolution. Get a quote to see how much you could save.
What type of van insurance do I need?
Commercial van insurance vs personal van insurance
Any driver van insurance explained
Van insurance groups explained
No claims bonus for van insurance
Hire and reward insurance for couriers
“81 million...” – Based on the total number of policies sold by Zego as of 23/07/25
“575K drivers...” – Based on the number of fixed policies sold by Zego as of 23/07/25
“96%..” – Based on Zego customers who have been insured on Sense policies and have a Driver Score, between 01/06/2025 and 01/08/2025